Giving goods on credit is a common part of B2B business. It can help suppliers build long-term relationships, increase sales and attract new customers. But when a buyer delays payment or fails to pay altogether, the same credit transaction can create serious cash-flow problems.
That is why businesses should check a buyer’s creditworthiness before giving goods on credit.
Creditworthiness refers to how reliably a buyer or business is likely to meet its financial payment obligations. Instead of relying only on personal references or verbal promises, suppliers can review business information, payment behavior, credit history and default records before deciding the appropriate credit terms.
In this guide, we will explain how to check a buyer’s creditworthiness and what information you should review before extending trade credit.
Why Should You Check a Buyer’s Creditworthiness?
When you sell goods on credit, you are effectively allowing another business to use your money until the invoice is paid.
For example, suppose you supply goods worth ₹5 lakh to a new buyer with a 60-day payment term. Until the buyer pays, your working capital is tied up in that transaction.
If the buyer pays on time, the transaction can strengthen your business relationship. But if the buyer repeatedly delays payments or defaults, you may face:
- Cash-flow problems
- Difficulty paying your own suppliers
- Increased outstanding receivables
- Collection and follow-up costs
- Higher risk of bad debts
- Disruption to day-to-day operations
A creditworthiness check helps you understand the buyer’s previous payment behavior and potential credit risk before you commit valuable inventory or working capital.
What Does Buyer Creditworthiness Mean?
Buyer creditworthiness is an assessment of a customer’s ability and willingness to pay for goods or services according to agreed payment terms.
For a B2B buyer, important factors can include:
- Previous payment behavior
- Credit history
- Existing outstanding obligations
- Default records
- Business identity and registration details
- Credit score or rating, where available
- Length and nature of business relationships
- Current exposure to your company
A buyer with a consistent payment history may present a different level of trade-credit risk from a buyer with repeated payment defaults.
However, no single indicator should be treated as a guarantee of future payment. A credit check should be part of a broader credit-management process.
7 Ways to Check a Buyer’s Creditworthiness Before Giving Credit
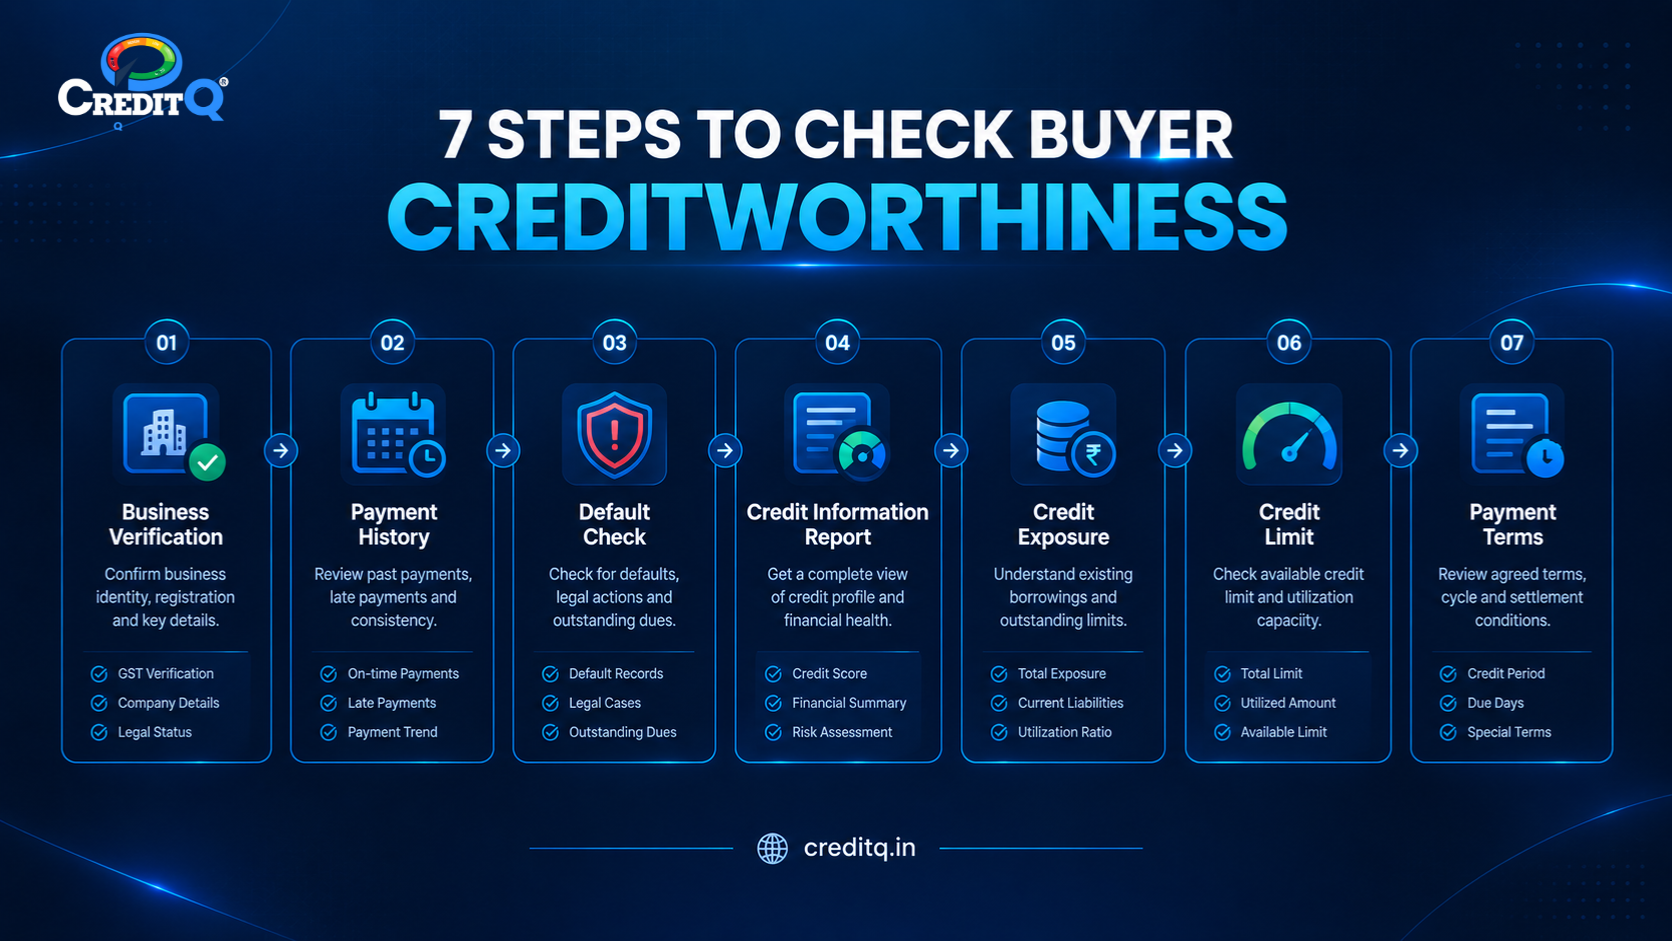
1. Verify the Buyer’s Business Details
Start by confirming that the buyer is a genuine and identifiable business.
Depending on the type of transaction, you may verify details such as:
- Legal business name
- GSTIN
- PAN
- Business address
- Contact details
- Nature of business
- Ownership or authorized representative
- Length of business operations
For Indian B2B transactions, GST and PAN details can help you identify the correct business before reviewing its credit information.
Do not rely solely on the information provided verbally by the buyer. Match the information across available business documents and records.
2. Review the Buyer’s Payment History
Past payment behavior is one of the most useful areas to examine when evaluating trade-credit risk.
Look for patterns such as:
- Payments made before the due date
- Payments made on time
- Frequent late payments
- Repeated payment extensions
- Unpaid invoices
- Outstanding balances
- Previous payment disputes
For example, if a buyer regularly takes 90 days to pay invoices despite agreeing to 30-day terms, that pattern should be considered when deciding future credit limits.
A payment history does not guarantee what will happen in the future, but it can provide useful evidence about previous payment behavior.
3. Check for Existing Default Records
Before giving substantial credit to a new buyer, check whether there are records of previous defaults.
A buyer that has been reported for non-payment by other businesses may require additional verification before you extend a large credit limit.
CreditQ provides a Credit Information Report (CIR) that can include information about financial dealings, business credit information and declared defaulter records.
This can give suppliers additional information to consider before entering into a credit transaction.
4. Get a Credit Information Report
One of the practical ways to evaluate a prospective business customer is to obtain a Credit Information Report.
According to CreditQ’s documentation, a CIR can be generated using a GST number or PAN and includes sections such as:
- CreditQ Score
- Demographic details of the entity
- Credit history summary
- Payment history for the last 12 months
- Defaulted transactions
This information can help a supplier understand the buyer’s previous credit behavior before deciding whether and how much trade credit to provide.
You can learn more about CreditQ’s Credit Information Report before conducting a buyer credit check.
5. Assess the Buyer’s Existing Credit Exposure
Do not look only at whether a buyer has paid in the past.
Also consider how much credit the buyer may currently have outstanding with your business and, where information is available, with other suppliers.
For example:
Buyer A
- Requested credit: ₹2 lakh
- Previous payments: Regular
- Outstanding balance: Low
Buyer B
- Requested credit: ₹10 lakh
- Previous delays: Frequent
- Outstanding obligations: High
Both buyers may generate the same amount of sales, but their trade-credit risk can be very different.
Understanding existing exposure can help you establish a sensible credit limit instead of approving every request automatically.
6. Start With a Controlled Credit Limit
You do not have to provide the maximum requested credit amount to a new buyer.
A practical approach is to start with a controlled limit and increase it after observing payment behavior.
For example:
First transaction: ₹1 lakh credit limit
↓
Payment performance reviewed
↓
Next transactions: Increase limit if appropriate
↓
Long-term relationship: Reassess periodically
This approach allows businesses to build credit relationships gradually instead of taking unnecessary exposure from the first transaction.
7. Set Clear Payment Terms Before Supplying Goods
A credit check is only one part of credit management.
Before dispatching goods, clearly define:
- Credit limit
- Payment due date
- Invoice terms
- Late-payment conditions
- Accepted payment methods
- Documentation requirements
- Process for handling disputes
Both parties should understand the payment terms before the transaction takes place.
A clear agreement can reduce misunderstandings and make payment follow-ups easier.
What Should You Look for in a Buyer Credit Report?
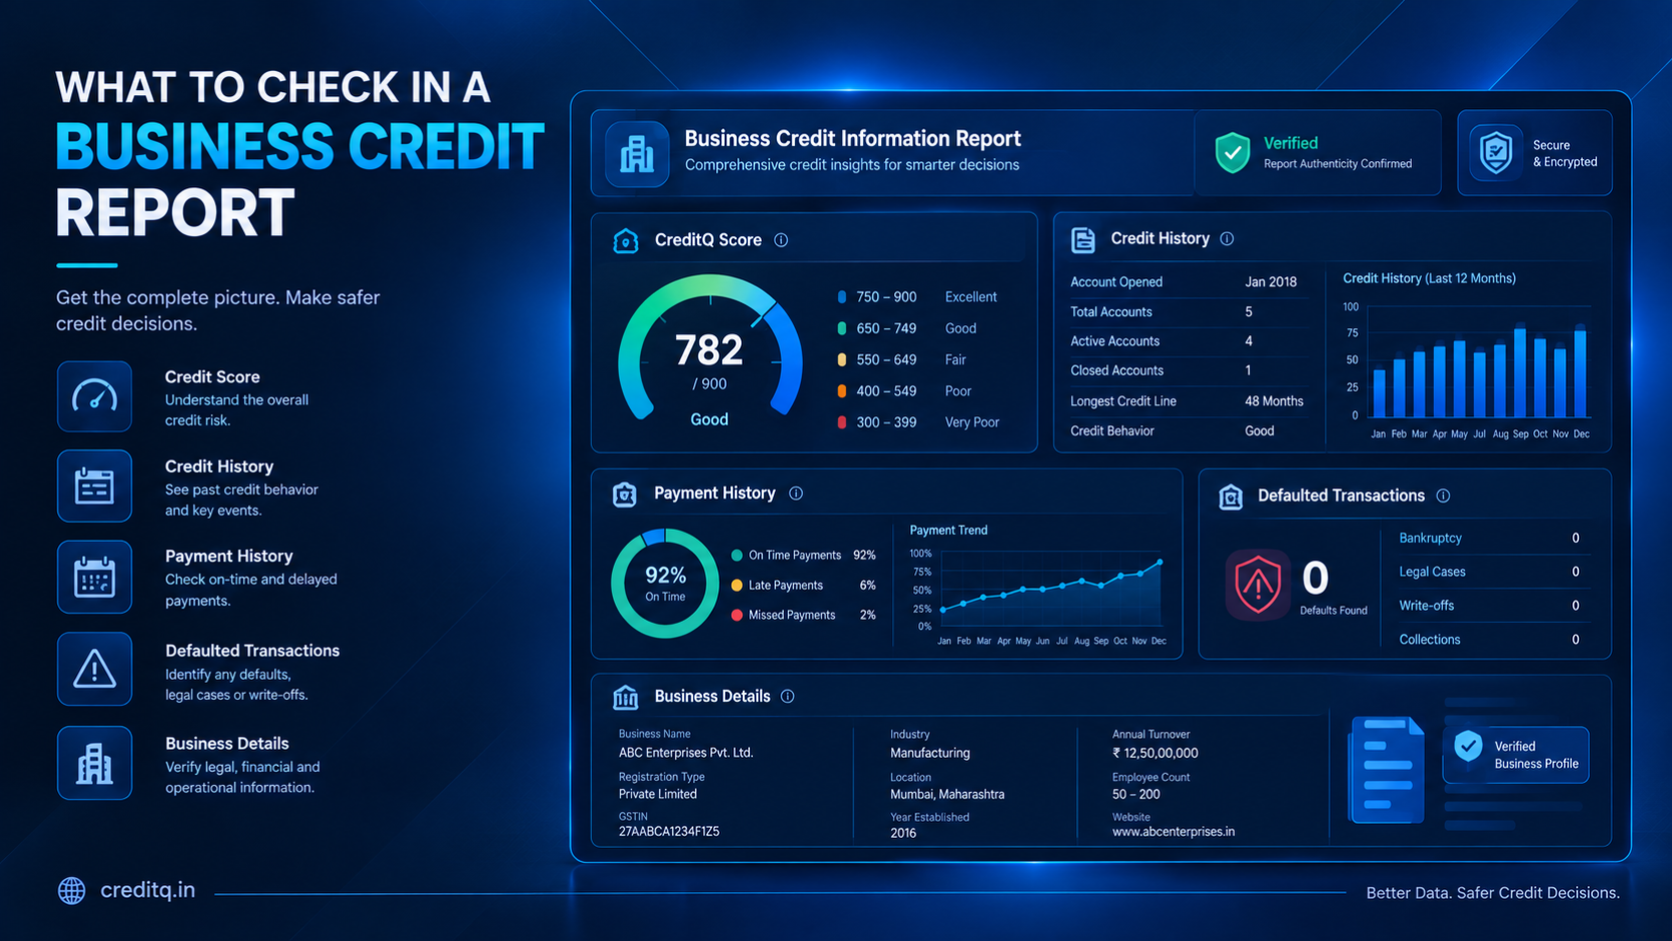
If you are reviewing a business credit report, focus on information that directly relates to payment risk.
| Information to Check | Why It Matters |
|---|---|
| Business identity | Helps confirm that you are evaluating the correct buyer |
| Credit score | Provides an additional indicator of credit behavior |
| Credit history | Shows previous credit-related activity |
| Payment history | Helps identify payment patterns |
| Defaulted transactions | Can indicate previous non-payment issues |
| Outstanding exposure | Helps understand potential repayment pressure |
| Business details | Helps validate the buyer’s identity and profile |
CreditQ’s CIR documentation specifically identifies CreditQ Score, credit history, payment history and defaulted transactions among the report sections.
Credit Score vs Payment History: Which Should You Check?
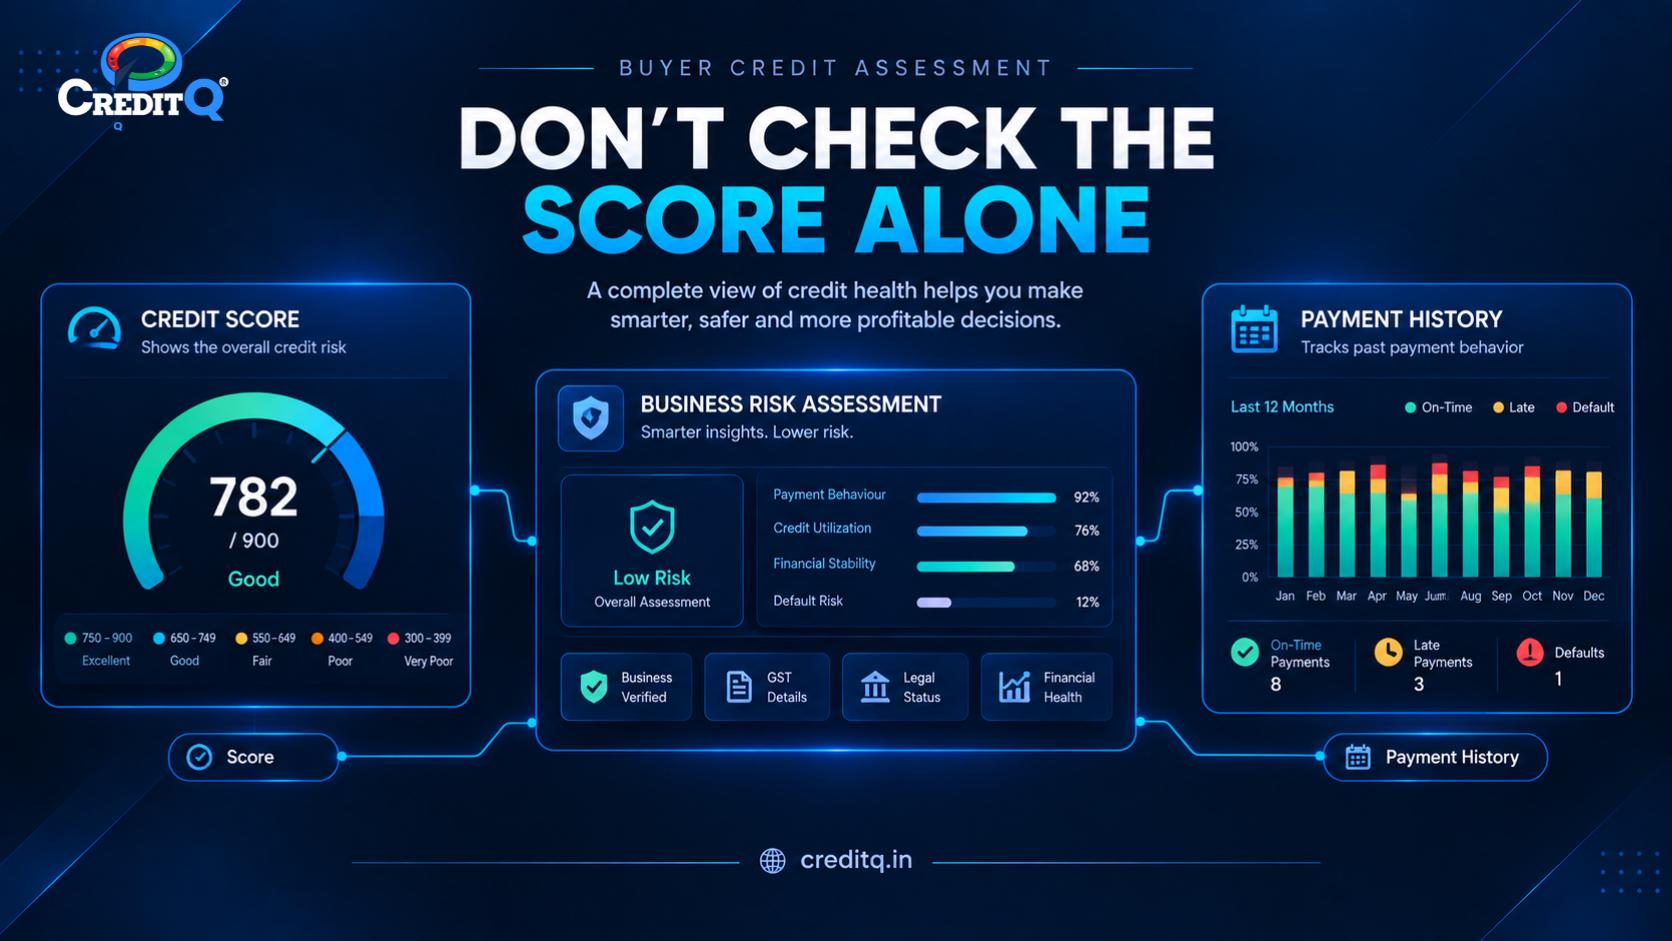
A credit score can be useful, but it should not be considered in isolation.
For trade-credit decisions, combine available score information with actual payment behavior and default records.
For example, a supplier could review:
Credit Score + Payment History + Default Records + Business Verification + Requested Credit Amount
This creates a broader view of the buyer rather than depending on one number.
What If the Buyer Has a Previous Default?
A previous default does not automatically tell you everything about the buyer’s current financial position.
Instead, investigate further.
You may want to consider:
- How recent was the default?
- Was the amount significant?
- Was the amount subsequently settled?
- Are there multiple default records?
- How has the buyer behaved since the incident?
- What credit limit are you considering?
- Can additional safeguards be used?
Based on the available information, a supplier may decide to reduce the credit limit, request advance payment, use milestone-based payments or ask for additional documentation.
The important point is to make the decision based on documented information rather than assumptions.
How CreditQ Can Help You Check Buyer Creditworthiness
CreditQ is a business credit management and information platform designed to help businesses make more informed credit decisions.
Its Credit Information Report provides information that can be reviewed before dealing with a prospective business or client. CreditQ states that its reports can highlight financial dealings, declared defaulter information, company credit score and other business information relevant to credit decisions.
The platform also provides business credit management and defaulter-reporting services aimed at helping businesses manage credit risk and payment-related issues.
If you regularly sell goods on credit, checking a prospective buyer before extending significant credit can become an important part of your business credit-management process.
A Simple Buyer Creditworthiness Checklist
Before giving goods on credit, use this checklist:
☐ Verify GST/PAN and business details
☐ Check the buyer’s credit information
☐ Review available payment history
☐ Check for previous default records
☐ Review the buyer’s credit score where available
☐ Assess the requested credit amount
☐ Set an appropriate credit limit
☐ Define payment terms clearly
☐ Keep invoices and transaction records
☐ Monitor payment behavior after the transaction
☐ Review the buyer periodically for larger credit exposure
Following a consistent checklist can make credit decisions more structured and reduce dependence on informal promises.
How Often Should You Recheck a Buyer’s Creditworthiness?
A buyer’s financial and payment situation can change over time.
Therefore, a creditworthiness check should not necessarily be a one-time activity.
Consider reviewing buyers again when:
- They request a major increase in credit
- Outstanding payments increase
- Payment delays become frequent
- You receive information about financial difficulties
- You are entering a significantly larger transaction
- A long-term credit relationship is being renewed
For high-value customers, periodic credit reviews can become part of your normal accounts-receivable and credit-management process.
Final Thoughts
Giving goods on credit can help businesses grow, but every credit transaction also creates financial exposure.
Before extending credit to a new buyer, verify the business, review payment behavior, check available credit information, look for previous default records and establish an appropriate credit limit.
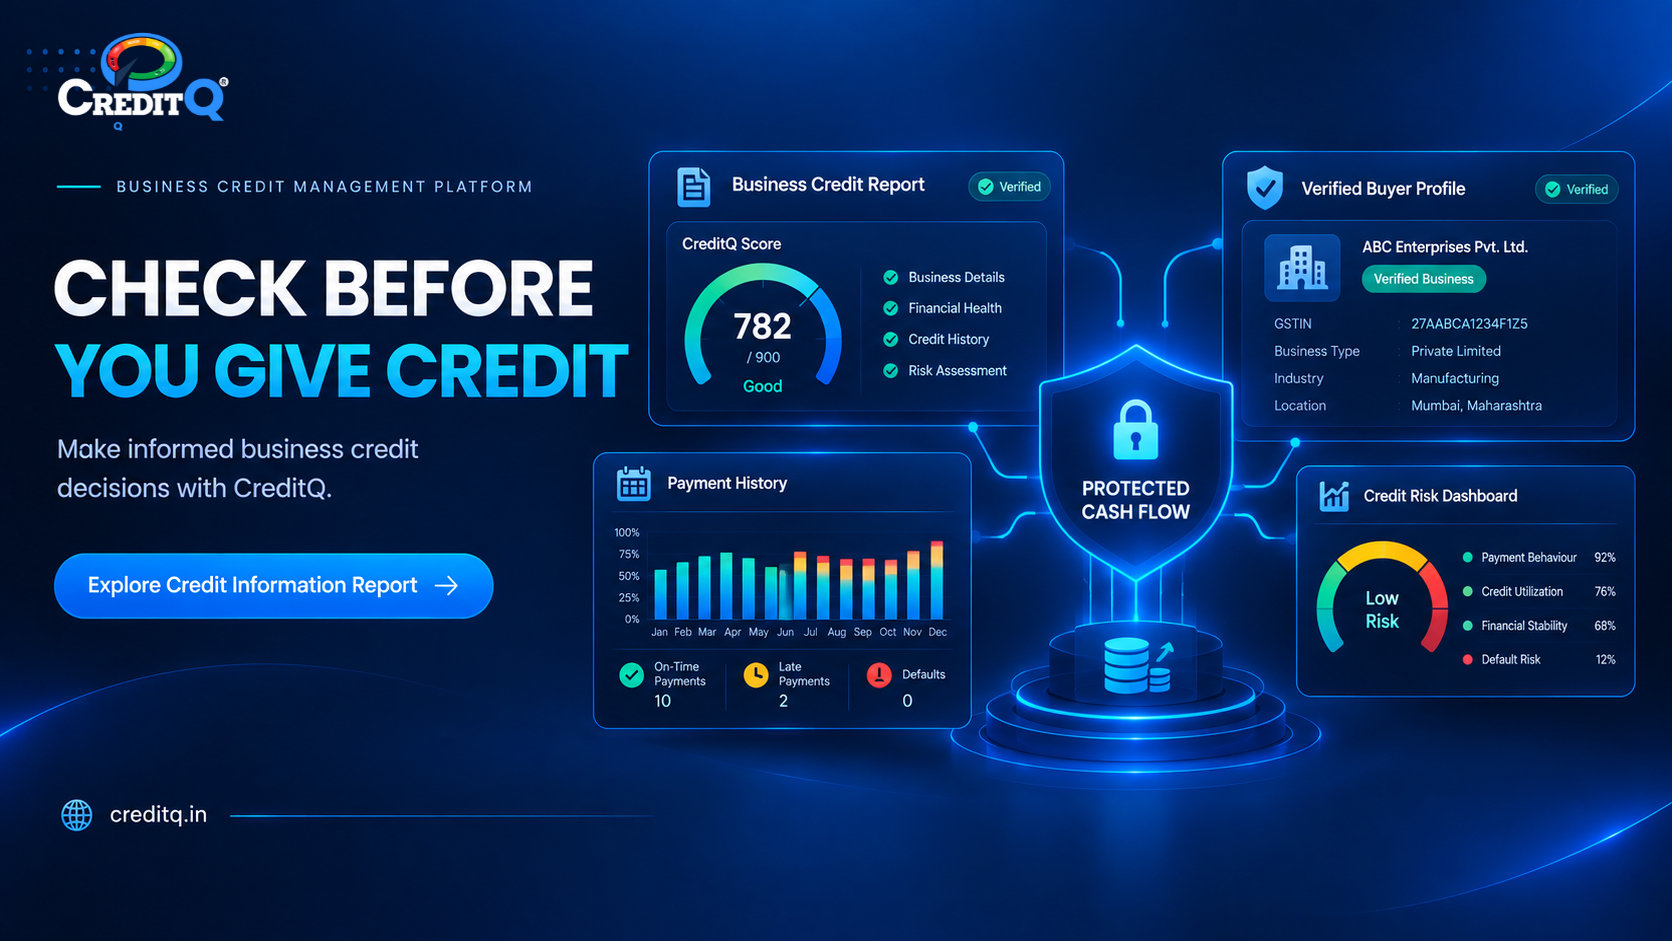
A Credit Information Report can provide additional information about a prospective buyer’s credit history, payment behavior and default records. CreditQ provides CIRs designed to help businesses make more informed decisions before dealing with prospective businesses or clients.
The goal is not to eliminate every credit risk. The goal is to make credit decisions using better information and a consistent process.
Before giving goods on credit, check first. Then decide the credit terms that fit the level of risk.
Protect Your Business Before Extending Credit
Before you supply goods to a new buyer, take a few minutes to understand their credit profile.
Check the buyer. Review the credit information. Set the right credit limit. Protect your cash flow.
Explore CreditQ Credit Information Report to get more information before making your next B2B credit decision.